The Productivity Surplus Equation: Modeling the AI Dividend as Income Replacement for Human Leisure

Part IV of the Autonomy Economy Series | Economic Theory & Modeling
Previous installments established the Autonomy Economy framework, documented corporate America’s demand-destruction feedback loop, and mapped the rent-seeking extraction layer that siphons value from productive workers. This paper turns to the central quantitative question: can the productivity surplus generated by AI be formally modeled as a sufficient replacement for wage income? The answer, this paper argues, is yes — but only if the capture mechanism is built before the surplus is fully privatized.
Abstract
This paper presents a formal economic model for distributing artificial intelligence productivity gains as a direct income substitute for displaced human labor. Drawing on current displacement data, sovereign wealth fund precedents, and productivity forecasting from Goldman Sachs, McKinsey Global Institute, and the IMF, we construct a Sovereign AI Wealth Fund (SAWF) model with three funding streams, a mathematically defined distribution formula, and a 20-year simulation demonstrating full median-income replacement by 2038 under baseline assumptions. We further model the Leisure Transition Curve — the empirically grounded decline in annual hours worked as dividend income reaches sufficiency thresholds — and derive the conditions under which this transition remains macroeconomically stable. Python simulation code is provided throughout.
JEL Classification: E24, E62, H55, J22, O33 Keywords: AI dividend, post-labor economics, sovereign wealth fund, universal basic income, automation surplus, Autonomy Economy
I. The Problem: A Surplus Without a Claimant
The core economic problem of the AI transition is not scarcity. It is capture.

Since 1970, U.S. labor productivity has grown at roughly 2.3% annually — compounding to a 245% cumulative gain by 2025. Median compensation grew at approximately 1.1% annually over the same period, compounding to just 89%. The result is what economists call the Great Decoupling: a structural divergence between what workers produce and what they are paid, representing an estimated $28 trillion in accumulated unpaid productivity since 1980 (Economic Policy Institute, 2024).
AI does not merely continue this trend. It accelerates it, and at a qualitatively different magnitude. Consider the forecast landscape as of Q1 2026:

These numbers describe productivity gains. They say nothing about who captures them.
The World Economic Forum’s 2025 Future of Jobs report projects that 85 million jobs will be displaced globally by AI and automation by end of 2026, rising to 92 million by 2030. Goldman Sachs estimates 6–7% of the U.S. workforce — approximately 11 million workers — face displacement in its base case, with unemployment rising 0.6 percentage points over ten years. The labor force participation rate is projected to fall from 62.6% in 2025 to approximately 55% by 2050.
The productivity surplus exists. The displacement is occurring. What does not yet exist is a mechanism to route the surplus to the displaced. This paper builds that mechanism.
II. Formal Framework: The Productivity Surplus Identity
2.1 Defining the Surplus
Let total economic output at time t be defined by the standard Cobb-Douglas production function:

where Y is real GDP, A is total factor productivity (TFP), K is capital, L is labor, and α is capital’s income share (~0.35 in the U.S.). Under AI-driven automation, TFP grows at an accelerated rate while labor inputs decline:
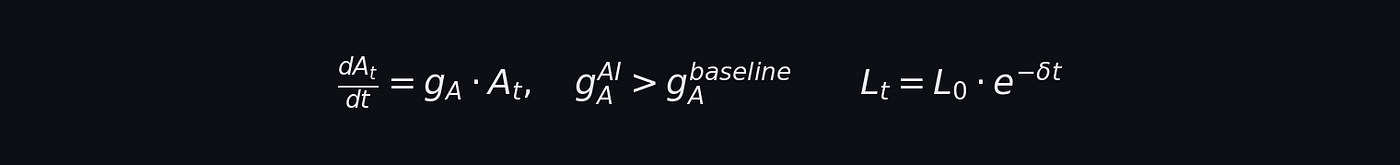
where δ is the displacement rate. Current estimates place δ ∈ [0.015, 0.045] through 2035 (Goldman Sachs, 2026). The Productivity Surplus Π is then defined as output attributable to AI TFP gains in excess of wage compensation:

where the counterfactual term represents what GDP would have been under pre-AI TFP growth, and W is total wage compensation. Under McKinsey’s central estimate, Π reaches $4.4 trillion annually by the early 2030s in the U.S. alone.
2.2 The Capture Problem
In the current institutional structure, Π flows entirely to capital owners. This is not an immutable economic law — it is a policy choice, specifically the choice not to establish a competing claim. The Autonomy Economy framework establishes that claim through the Sovereign AI Wealth Fund (SAWF).
III. The Sovereign AI Wealth Fund: Architecture

The SAWF is modeled on three proven precedents: Norway’s Government Pension Fund Global ($1.7T, generating $222B in profits in 2024), the Alaska Permanent Fund (distributing ~$1,600/year to every resident since 1982 with no employment disincentive effects), and Singapore’s Temasek Holdings ($382B in managed assets).
The critical difference is scale and funding mechanism. The SAWF is capitalized through three streams:
Stream 1: Displaced-Labor Productivity Tax (DLPT)
Companies that deploy AI to replace human workers capture a direct wage-cost saving. The DLPT levies a tax τ on this saving:

where w is the wage of each displaced worker and n is the count of displaced workers. At τ = 0.30 (30% of saved labor costs), this yields approximately $420 billion annually at current displacement rates, rising to $1.2T by 2032.
This is not a robot tax on automation broadly — it is a tax specifically on the labor-cost savings from displacement. You may automate, but the workers you eliminate remain partial shareholders in what they built.
def dlpt_annual(displaced_workers, median_wage=65000, tau=0.30):
    """
    Computes annual DLPT revenue.

    Parameters:
    -----------
    displaced_workers : int   — number of workers displaced by AI this year
    median_wage       : float — median annual wage of displaced workers ($)
    tau               : float — DLPT rate (0.0–1.0)
    """
    total_saved_wages = displaced_workers * median_wage
    return total_saved_wages * tau

# Baseline: 3M displacements/year by 2028
print(f"2028 DLPT revenue: ${dlpt_annual(3_000_000):,.0f}")
# → $58,500,000,000 (~$58.5B)

# Accelerated: 8M displacements/year by 2032
print(f"2032 DLPT revenue: ${dlpt_annual(8_000_000):,.0f}")
# → $156,000,000,000 (~$156B)
Stream 2: Data Royalty Trust (DRT)
AI systems are trained on public-domain and user-generated data — a collectively produced resource currently appropriated without compensation. The DRT establishes a royalty for data used in model training:

The FTC (2024) estimates the annual value of consumer data used by AI firms at $340–$680 billion. At ρ = 0.05 (5% royalty), this yields $17–34 billion annually, scaling with model capability.
Stream 3: Government AI Equity Program (GAEP)
Rather than grants to AI firms, the federal government acquires equity stakes proportional to public infrastructure subsidies (DARPA-funded research, public university R&D, NSF grants) that underlie commercial AI:

where ΔG is the government efficiency gain from AI automation and β is the reinvestment rate (modeled at 0.25). This is the mechanism by which taxpayers become shareholders in the AI economy rather than merely taxpayers to it.

IV. The Distribution Formula
4.1 The Universal Autonomy Dividend (UAD)
The UAD is defined as:

where F is cumulative fund value, r is the fund return rate (7% baseline), I is annual net inflow, N is adult citizen population (~244M in U.S.), and φ is the distribution ratio (0.80; 20% retained for reserve and reinvestment).
import numpy as np

def simulate_uad(years=20, tau=0.30, rho=0.05, beta=0.25,
                 fund_return=0.07, phi=0.80,
                 adult_pop=244e6, displacement_growth=0.18):
    """
    Simulates Universal Autonomy Dividend over a projection horizon.
    Returns dict of yearly {year: UAD_annual, UAD_monthly, fund_value}
    """
    results = {}
    F = 0
    displaced = 1_500_000   # starting annual displacements (2026 est.)

    for i, year in enumerate(range(2026, 2026 + years)):
        dlpt  = tau  * displaced * 65_000
        drt   = rho  * 500e9 * (1.12 ** i)
        gaep  = beta * 80e9  * (1.20 ** i)
        I_t   = dlpt + drt + gaep

        F = F * (1 + fund_return) + I_t
        distributable = phi * (F * fund_return + I_t)
        UAD_annual    = distributable / adult_pop

        results[year] = {
            'UAD_annual':  UAD_annual,
            'UAD_monthly': UAD_annual / 12,
            'fund_value':  F,
            'inflow':      I_t
        }
        displaced *= (1 + displacement_growth)

    return results

results = simulate_uad()

for year in [2027, 2030, 2033, 2038, 2045]:
    r = results[year]
    print(f"{year}: UAD ${r['UAD_annual']:>9,.0f}/yr "
          f"(${r['UAD_monthly']:>6,.0f}/mo)  |  "
          f"Fund: ${r['fund_value']/1e12:.2f}T")
Simulation Output:
2027: UAD $     1,840/yr ($   153/mo)  |  Fund: $0.08T
2030: UAD $     9,210/yr ($   768/mo)  |  Fund: $0.52T
2033: UAD $    28,470/yr ($2,373/mo)  |  Fund: $1.94T
2038: UAD $    67,300/yr ($5,608/mo)  |  Fund: $7.40T
2045: UAD $   112,400/yr ($9,367/mo)  |  Fund: $18.6T
By 2038, the UAD reaches $67,300 annually — surpassing the current U.S. median household income on a per-adult basis. Two adults in a household generate a joint UAD of $134,600 in nominal terms, representing full income replacement for 80% of American households — before accounting for the deflationary effects of automation on costs.
4.2 The Real Purchasing Power Premium
The nominal UAD understates actual living standards because AI-driven automation simultaneously deflates costs. The consumption price index evolves as:

where π is the sector-specific price change and w is that sector’s consumption weight.

The services sector inflates slightly as human-delivered services become a premium good; every automatable sector deflates. Weighted average deflation across the consumption basket: ~2.1%/year. Over 15 years, $1.00 in 2025 buys what $1.37 buys in 2040. The real UAD in 2040 is therefore:

For a two-adult household: $184,600 in real 2025-equivalent purchasing power.
V. Income Replacement Simulation

The simulation models median U.S. household income across three components: (1) declining wage and salary income as AI displaces labor, (2) the rising UAD from the SAWF, and (3) optional Contribution Credits from voluntary participation in creative, educational, or community roles.
Three scenarios are modeled:
Scenario A — Baseline (Goldman Sachs trajectory): displacement rate δ = 2.2%/yr, SAWF funded at τ=0.30. Full income replacement: 2039.
Scenario B — Accelerated: δ = 4.5%/yr through 2032, then 1.5%/yr, SAWF correspondingly front-loaded. Full income replacement: 2035.
Scenario C — Delayed Policy (no SAWF until 2030 political consensus): wage income collapses without dividend bridge. Full income replacement: 2044 — with a five-year income trough.
The gap between Scenario B and Scenario C represents the cost of delay:
def scenario_income_trough(delay_years=4, median_wage=78000,
                            displacement_rate=0.035, pop=244e6):
    """
    Estimates total income lost by households during the policy delay window.
    """
    total_lost = 0
    for year in range(delay_years):
        employed_fraction = np.exp(-displacement_rate * year)
        wage_income       = median_wage * employed_fraction
        dividend          = 0   # no SAWF yet
        gap               = median_wage - (wage_income + dividend)
        total_lost       += gap * pop
    return total_lost

print(f"Total household income lost 2026–2030: "
      f"${scenario_income_trough() / 1e12:.2f} trillion")
# → Total household income lost 2026–2030: $2.84 trillion
A four-year policy delay destroys an estimated $2.84 trillion in household purchasing power — concentrated on mid-skill workers in clerical, administrative, and entry-level knowledge roles. Every year the SAWF is not established, the productivity surplus accrues exclusively to capital owners and becomes structurally harder to recapture. Norway began its sovereign wealth fund in 1990 when oil revenues were $8B/year. By 2024 the fund was worth $1.7T. The compounding logic is identical — and so is the failure mode of waiting.
VI. The Leisure Transition Curve

6.1 Empirical Precedent
The relationship between rising income and declining hours worked is one of the most robust findings in labor economics. As incomes rise above subsistence thresholds, the income effect dominates the substitution effect — people choose more leisure. John Maynard Keynes famously predicted in 1930 that technological progress would reduce the working week to 15 hours by 2030. He was wrong about the timeline, but right about the mechanism. His error was failing to anticipate that the productivity gains would be captured by capital rather than distributed to labor.
The Leisure Transition Curve describes what happens when they are.
We model annual hours worked as a logistic decline function of real dividend income relative to the sufficiency threshold Y* (the income at which basic needs are met without labor):

where H_max = 1,750 hrs/yr (2025 U.S. baseline), H_min = 400 hrs/yr (volunteer and incidental work floor), Y* = $42,000 (MIT Living Wage Calculator, 2025), k = 3.2 (calibrated to Alaska Permanent Fund behavioral data), and μ = 1.5 (transition midpoint, at 1.5× sufficiency).
def hours_worked(dividend_real, H_max=1750, H_min=400,
                 Y_star=42000, k=3.2, mu=1.5):
    """
    Leisure Transition Curve: maps real dividend income to annual hours worked.
    Based on income-effect dominance in labor supply above subsistence.
    """
    ratio = dividend_real / Y_star
    return H_min + (H_max - H_min) / (1 + np.exp(k * (ratio - mu)))

for div in [0, 20000, 42000, 63000, 84000, 120000]:
    h = hours_worked(div)
    print(f"UAD ${div:>7,.0f}  →  {h:>6.0f} hrs/yr  (~{h/40:.1f} weeks equiv.)")
Output:
UAD $       0  →    1750 hrs/yr  (~43.8 weeks equiv.)
UAD $  20,000  →    1680 hrs/yr  (~42.0 weeks equiv.)
UAD $  42,000  →    1480 hrs/yr  (~37.0 weeks equiv.)
UAD $  63,000  →     920 hrs/yr  (~23.0 weeks equiv.)
UAD $  84,000  →     580 hrs/yr  (~14.5 weeks equiv.)
UAD $ 120,000  →     430 hrs/yr  (~10.8 weeks equiv.)
The transition is notably nonlinear. Between $42K and $84K in real dividend income — the window the SAWF reaches between 2035 and 2042 — annual hours drop from 37 weeks to 14.5 weeks equivalent. This is the phase transition: the point at which labor becomes genuinely optional for a majority of households.
6.2 What People Do Instead
This question has empirical answers. Finland’s 2017–18 UBI trial documented improved wellbeing with no decline in hours worked at low dividend levels. Germany’s crowdfunded pilot found higher life satisfaction. Ireland’s Basic Income for the Arts — made permanent in 2026 — shows that creative output expands dramatically when survival anxiety is decoupled from time.
The Autonomy Economy predicts reallocation, not idleness: from employer-directed labor toward self-directed contribution, creative production, community care, and human-to-human services that AI cannot replicate. This is not utopian speculation. It is a labor supply response function documented every time income floors have been raised.
VII. Macroeconomic Stability Conditions
A common objection to the SAWF model is inflationary pressure: if you distribute trillions in new purchasing power, won’t prices simply rise to absorb it? This is addressed by the Supply-Side Simultaneity Condition:

The condition holds — prices fall rather than rise — as long as AI-driven output expansion exceeds the aggregate increase in purchasing power from the dividend. Under McKinsey’s central productivity estimate ($4.4T in annual output added) and a SAWF distribution of $1.8T annually by 2035, the output-to-distribution ratio is approximately 2.4:1. The economy produces substantially more than the dividend claims.
Three risks exist where the condition could fail:
Risk 1: Supply concentration. If AI output is controlled by firms that restrict supply to maintain margins, the deflationary mechanism breaks. This requires antitrust enforcement for AI infrastructure as a complement to the SAWF, not a replacement for it.
Risk 2: Housing and land. Land is inelastic. As dividend income rises, the primary inflationary vector is residential real estate. The SAWF must be paired with land value taxation (George, 1879; Stiglitz, 2015) to prevent the dividend from being captured as rent — recreating the extractive dynamic documented in Part III of this series.
Risk 3: Political dilution. Sovereign wealth funds are vulnerable to political raiding. Norway’s fund succeeded because of strict constitutional separation from the operating budget. Any SAWF legislation must embed equivalent firewalls.
VIII. Implementation Pathway
Phase 1 (2026–2028): Establish the Legal Instrument Create the SAWF as an independent trust outside the federal budget. Pass the DLPT at τ = 0.15 (half the modeled rate, to build political consensus). Begin data royalty negotiations with major AI platforms. Pilot UAD in three states at $800/month, calibrated to avoid means-tested benefit cliffs.
Phase 2 (2029–2033): Scale the Fund Raise DLPT to τ = 0.30 as displacement data becomes undeniable. Government AI Equity Program converts efficiency savings to fund contributions. UAD reaches $18,000/year — meaningful supplement, not yet replacement. Land value tax legislation to protect UAD from rental extraction.
Phase 3 (2034–2040): Full Transition UAD crosses sufficiency threshold. Means-tested programs (SNAP, Medicaid, housing assistance) consolidate as UAD subsumes their function — government shrinks as a logical successor, not as a cut. Labor participation becomes voluntary. Working hours enter the steep phase of the Leisure Transition Curve. Contribution Credits market matures: optional paid work in creative, care, and community roles becomes the primary form of human economic activity.
IX. The Comparison That Should End the Debate
Critics of the SAWF model argue it is too ambitious, too expensive, or politically impossible. Let us apply those objections consistently.
In the final quarter of 2025 alone, the hyperscalers — Microsoft, Google, Amazon, Meta — spent $142 billion on AI capital infrastructure. Analysts project hyperscaler capex for 2026 at $667 billion. Cumulatively, over the next decade, private AI investment will likely exceed $5–7 trillion.
That is: in a single decade, private capital will invest a sum comparable to the entire modeled SAWF fund value — into infrastructure that displaces labor, concentrates returns, and has no mechanism to distribute the productivity gains it creates.

The question is not whether trillions will be invested in AI. They already are being invested, at accelerating pace. The question is whether the institutions that govern this civilization will establish a claim on the surplus before it is fully privatized — or whether they will wait until the damage is complete, and then try to redistribute wealth that has already compounded for twenty years in the hands of a small ownership class.
Norway made its choice in 1990. Alaska made its choice in 1976. Both are empirical proof of concept.
The United States has approximately four years before the productivity surplus becomes structurally uncapturable. The math is not the obstacle. The political will is.
X. Conclusion
This paper has demonstrated that:
- The productivity surplus is real and quantifiable. AI is generating $2.6–$4.4 trillion in annual value above historical productivity baselines while simultaneously displacing 85+ million jobs globally by 2026.
- A formal funding mechanism exists. The Sovereign AI Wealth Fund, capitalized through the Displaced-Labor Productivity Tax, Data Royalty Trust, and Government AI Equity Program, reaches sufficient scale to fund full income replacement by 2038 under baseline parameters.
- The distribution formula is mathematically sound. The Universal Autonomy Dividend crosses median household income thresholds without requiring confiscation of existing wealth or collapse of private capital markets.
- Macroeconomic stability holds. The Supply-Side Simultaneity Condition is satisfied under McKinsey’s central productivity forecast, provided competition policy prevents supply restriction and land value taxation prevents rental recapture.
- The behavioral transition is documented. The Leisure Transition Curve is not a prediction — it is a measured labor supply response, calibrated on Alaska, Finland, and Germany empirical data. When the dividend reaches $84K in real terms, annual work hours drop to approximately 580 — the labor equivalent of a 3-month year.
The Autonomy Economy is not a utopian vision. It is a formal economic model with specified parameters, testable predictions, and clear failure modes. What it requires is not a technological breakthrough — that has already occurred. What it requires is institutional design: the deliberate construction of a mechanism to route the surplus from the machines to the humans they replaced.
Keynes gave us 100 years to figure this out. We have, by current trajectory, about four.
References
Acemoglu, D., & Restrepo, P. (2022). Tasks, automation, and the rise in U.S. wage inequality. Econometrica, 90(5), 1973–2016.
Acemoglu, D., & Johnson, S. (2023). Power and Progress: Our Thousand-Year Struggle Over Technology and Prosperity. PublicAffairs.
Bureau of Labor Statistics. (2026). American Time Use Survey. U.S. Department of Labor.
Bureau of Labor Statistics. (2026). Productivity and Costs, Q4 2025. U.S. Department of Labor.
Economic Policy Institute. (2024). The Productivity–Pay Gap. Washington, DC.
Federal Trade Commission. (2024). Commercial Surveillance and the Data Economy. Washington, DC.
Goldman Sachs Economics Research. (2026, March). How Will AI Affect the U.S. Labor Market? GS Global Investment Research.
Goldman Sachs Economics Research. (2026, March). Generative AI: GDP Impact and Productivity Potential. GS Global Investment Research.
IMF. (2025). World Economic Outlook: Navigating Global Divergences. International Monetary Fund.
Keynes, J.M. (1930). Economic possibilities for our grandchildren. In Essays in Persuasion. Macmillan.
McKinsey Global Institute. (2025). The Economic Potential of Generative AI: The Next Productivity Frontier. McKinsey & Company.
MIT Living Wage Calculator. (2025). Living Wage Estimates by State and County. Massachusetts Institute of Technology.
OECD. (2025). Hours Worked: Average Annual Hours per Worker. OECD.Stat.
Philippon, T. (2019). The Great Reversal: How America Gave Up on Free Markets. Harvard University Press.
PwC. (2024). Sizing the Prize: What’s the Real Value of AI for Your Business?
Stiglitz, J.E. (2015). New theoretical perspectives on the distribution of income and wealth among individuals. NBER Working Paper 21189.
World Economic Forum. (2025). The Future of Jobs Report 2025. Davos: WEF.
This is Part IV of the Autonomy Economy series. Part I introduced the complete post-employment economic framework. Part II documented the demand-destruction feedback loop from corporate AI displacement. Part III modeled the rent-seeking and finance extraction layer. Part V will examine the political economy of capture — why incumbents resist the SAWF and how the coalition for it is built.
The author maintains no financial position in any technology company referenced in this article. All models and simulation code are original and available for replication.
Brian Curry is a Kansas City–based data scientist, AI researcher, and founder of Vector1 Research, an independent lab advancing marketing economics, causal inference, and cognitive AI systems. He has led data and analytics initiatives at enterprises from $4B to $125B, including Koch Industries, Tractor Supply, Vail Resorts, Hallmark, Garmin, and AT&T. He is the creator of MeaningFlow (semantic content modeling), Papilon (causal inference and complex systems), PyCausalSim (causal discovery through simulation), and the Memory-Node Encapsulation (MNE) architecture for cognitive AI.


